

TL;DR: today vs. yesterday
Two things broke at once: Ansarallah completed its sweep of Yemen's entire Red Sea coastline and now holds both sides of Bab el-Mandeb, and Saudi Arabia shut in the East-West pipeline after drone strikes gutted two pump stations - removing the last major Hormuz bypass. Riyadh then chose not to retaliate, called Washington twice, and got told no; Pakistan declined too. Meanwhile a 0.3% core CPI print flipped Goldman, JPMorgan, MUFG and Citi to a September hike inside a single afternoon, with the 30Y closing at its highest weekly level since 2004.
1. Critical Alerts
Bab el-Mandeb is fully under Ansarallah control. Perim/Mayyun island fell and Yemeni government forces announced withdrawal (KobeissiLetter, MenchOsint); the entire Red Sea coastline went in an 18-hour offensive (AJENews, AJEnglish). Confidence: HIGH.
Saudi East-West pipeline shut in after multiple strikes. ~7mn bpd capacity, the primary Hormuz bypass (KobeissiLetter); Saudi Energy Ministry confirmed shutdown "as a precaution" with multiple injuries (MenchOsint, zerohedge). Satellite imagery shows damage at the Al-Dhekraa and Al-Misbaah pump stations (dana916). Confidence: HIGH.
September Fed hike is now the street's base case. Core CPI 0.3% m/m vs 0.2% expected (zerohedge); odds ran to 88% (Barchart), Goldman threw in the towel (zerohedge), JPMorgan moved to September+December (zerohedge), MUFG (zerohedge) and Citi (zerohedge) followed. Confidence: HIGH.
MBS called Trump twice asking for strikes on the Houthis. Trump declined (unusual_whales, Osinttechnical, tparsi, per Axios). Pakistan reportedly refused a Mecca Defense Treaty call-up, arguing the pact doesn't cover "pre-existing conditions" (DailyIranNews). Confidence: HIGH on the Trump refusal, LOW on the Pakistan detail.
US average retail diesel topped $6/gal for the first time (zerohedge); California became the first state to average $8 with stations already past $9 (GasBuddyGuy), and $10 pumps are being reported (Megatron_ron, DA_Stockman). Confidence: HIGH.
2. Core Themes
Yemen: the entire Red Sea coastline falls in an 18-hour push - both shores of Bab el-Mandeb now Ansarallah's
The Ansarallah statement puts hard numbers on the campaign launched 3 September: six districts across Taiz and Hodeidah, 5,400 km², seven Saudi-backed divisions comprising 38 brigades engaged, 32 intercept operations and nine aircraft claimed shot down (Aresinfoservice).
Same statement: navigation declared safe for all shipping except Saudi vessels, under a stated "siege for a siege" equation.
Bloomberg's framing - Houthi gains leave MBS with few good options; escalate a campaign that has failed for years, or accept rebel leverage over a route that has become more important to Saudi exports (bonzerbarry).
Reuters reporting says the coastal advance came with direct IRGC guidance, opening a new front in Iran's war with the US (zerohedge).
A commander's pitch, on video: they no longer need drones or missiles - artillery positioned along the coast covers the strait (MenchOsint, BashaReport).
Taizz is the live front. Ansarallah took Al-Mazraq and Jirdad/Jabal Qardad mountain, ~12 km from the last PLC highway out of the city, +43.7 km² in 24 hours (AMK_Mapping_, OSINTWarfare).
Marib is contested but not falling: artillery exchanges through 02:00, and claims of clashes inside Marib city are incorrect (SprinterPress) - compare the earlier "heavy confrontation" report (MenchOsint).
PLC jets flying from Saudi bases struck launcher positions in the mountains north of Taizz and Mount Oman (Alsakaniali), and the Saudi Air Force claimed vehicle/weapons destruction at Al-Mokha (MenchOsint) - equipment its own side left behind.
Captured US-supplied vehicles and weapons are circulating on video (steve_hanke, tparsi); withdrawing Saudi-backed fighters are selling their weapons rather than fighting (MenchOsint).
Overnight sirens in Taif, Khamis Mushait and Sharurah, with launches likely aimed at King Fahd and King Khalid air bases (MenchOsint, MenchOsint).
Confidence: HIGH (multi-source OSINT plus wire confirmation).
Saudi Arabia: East-West pipeline shut in, and Riyadh decides not to respond
Saudi Arabia says the attack came from Iraqi territory and has explicitly opted not to retaliate at this stage, to give Baghdad room to act (MenchOsint, MyLordBebo). Iraq ordered an investigation and condemned the strike (AJENews).
If Iraqi-launched, the drones flew 800+ km; the prior attack from Iraq hit Abqaiq on 28 July (MenchOsint).
Attribution is genuinely contested in the feed: US officials say drones from Iraq (zerohedge, DavidLe76335983); others read the before/after imagery as ~1,000 km missile strikes (imetatronink) or Ansarallah with Iranian long-range weapons (Pataramesh). One account reports Baghdad sacked a general over it (hashurtag). Confidence: MEDIUM on Iraq-origin, LOW on any single actor.
Repair window: temporary fix possible in days, permanent longer, with oil spills at three points (MarhelmData). Only one fresh Yanbu cargo appeared in tanker data, consistent with a real shut-in (MarhelmData).
Scale: smoke stretched 100+ km across the desert, visible from orbit at global zoom (SoarAtlas, MarioNawfal, Frank_Stones); Reuters reviewed satellite imagery of the smoke before confirmation (ResisttheMS).
Saudi output context: Riyadh told OPEC August crude collapsed 1.9mn bpd to 6.238mn bpd, lowest since 1990 (wmiddelkoop). Saudi plus Russia together pumped ~5.5mn bpd less than January (JavierBlas).
Red Sea routing math: voyages that reached the Arabian Sea in four days now take a ~34-day Cape detour (MenchOsint).
CENTCOM's commander was in the kingdom and ~100 US advisers are being sent to help fight Ansarallah (ejmalrai, zerohedge); a four-digit-callsign C-17 ran to Riyadh (MenchOsint).
The bear thesis, stated plainly: ~54% of Saudi government revenue is oil, and the transmission runs Aramco → revenues → PIF → banks, with Saudi Awwal Bank flagged on sovereign/public-sector exposure above 2x CET1 (realTimHack). Confidence: LOW, single source, but the mechanism is specified.
Timing note worth keeping: the announcement landed after the US cash close on Friday (DarioCpx), and major outlets treated the fires as a footnote for most of the session (Mark4XX, DarioCpx).
Confidence: HIGH on the shut-in itself.
Fed: core CPI 0.3% flips the whole street - and the 30Y closes at a 2004 high
Headline CPI +0.4% m/m / 3.4% y/y, core +0.3% m/m / 2.4% y/y (zerohedge). Core y/y is actually the lowest since 2021 (Hedgeye) - and hike odds soared anyway.
The deciding line item: wireless telephone services +5.9% m/m, ~10bp of core, which Goldman confirms moved core from 0.2% (no hike) to 0.3% (hike) (zerohedge). BofA calls it a one-off from AT&T plan retirement and admin fees (zerohedge). Gasoline +3.9% carried over a third of the headline (zerohedge).
Markets now see a base case of four hikes by July 2027 - against four cuts priced for the same window at the start of 2026, a 200bp swing in nine months (KobeissiLetter).
Long end: 30Y closed at its highest weekly level since 2004 (Hedgeye), 2Y broke 4.65%, a two-year high (Hedgeye), 10Y ran to 4.975% (zerohedge). France's 30Y hit a 24-year high (Barchart).
The US-China 10Y spread hit 3.17pp, the widest on record (Barchart), and price-sensitive investors now hold 57% of Treasuries, most this century (Barchart).
Fiscal backdrop: FY2026 deficit at $1.97tn with a month to go, interest at a record $1.4tn (zerohedge), and interest expense set to pass Social Security as the largest outlay by end-2028 (zerohedge). OECD gross interest hit $2.24tn in 2025, +$180bn y/y (KobeissiLetter).
CBO now projects debt/GDP at 156% by 2050; Treasury's own estimate is 213% - 57 points apart, and both assume no recession for the whole period (KobeissiLetter).
Trump says the $5,000 "dividend" "will happen" (KobeissiLetter), with Lutnick claiming it won't rely on tax funds (zerohedge).
The dissent worth reading: hikes raise interest, cut receipts, push interest/receipts past 110% and force the Fed to print the interest anyway (LukeGromen). A second take: the hawkish posturing is designed to shake people out of assets into cash, and no hike actually arrives (potassium_phd).
Consumer side is not cooperating: UMich sentiment 47.8 vs 51.0 expected, expectations 45.8 and near record lows, 1-yr inflation expectations 4.6% (zerohedge). Ground beef at a new all-time high, over $7/lb (Barchart, Hedgeye) - while egg prices collapsed 68% since end-July (Barchart).
Confidence: HIGH.
Oil: Shanghai crude at a record $16 over Brent as the physical market stops pretending
Shanghai crude hit $121 on a Chinese buying spree, with the spread to Brent at $16, an all-time high (zerohedge).
The full physical picture: DME Oman ~$122, Murban ~$122.50, Dubai/Oman $19-30 over paper on grades that used to trade $1-4 under Brent - a spread that wide for that long is rationing, not risk premium (Mark4XX).
IEA: another 95mn barrels drawn in August, 507mn since February, with inventories still falling ~3mn bpd (Mark4XX). Brent neared $110 then tumbled on an IEA demand-destruction warning (zerohedge).
Freight: supertanker rates near a record $1mn/day (zerohedge); the $700k level came after a 354% rally (chigrl), and the tanker ETF has gone vertical (Barchart).
Refining is the choke: the White House is weighing Defense Production Act authority to expand US refining capacity (zerohedge) - refiners sold off on the headline, and capacity takes years, not quarters (chigrl).
Piper Sandler warns shrinking buffers collide with winter demand (zerohedge); Energy Aspects calls it an inflection point (zerohedge); coal is nearing a breakout as utilities revert ahead of winter (zerohedge).
Jeff Currie puts the odds of $5 gas by the midterms at "extremely high" (zerohedge) - which is why Brent is now being read as a midterm variable (themarketear).
China raised retail gasoline 260 yuan/tonne and diesel 250 yuan/tonne from Saturday, citing US-Iran tensions (MilitarySummary).
LNG is rotating the same way: Qatar - one of the largest exporters - is seeking US LNG supply through 2031 after losing capacity, with Venture Global, Cheniere and Woodside in the mix (chigrl, Macrobysunil).
Confidence: HIGH.
Hormuz: the GCC six sit down with Araghchi in Salalah on Monday - Tehran's price is "everything"
A six-member Gulf bloc is considering meeting Iranian officials next week, the first such gathering since the war began (annmarie, Bloomberg), with FT placing it in Salalah, Oman on Monday (MilitarySummary) - and Gulf states framed as requesting it urgently now that Bab el-Mandeb has gone (IranObserver0, zerohedge).
Tehran's opening position: talks are useless unless Washington accepts all of Iran's demands, per the head of parliament's national security committee (AJEnglish, Ebrahimazizi33).
Naval picture: Iran resumed anti-ship missile launches toward a US carrier and escorts (HormuzReport); WSJ-sourced reporting says recent attacks failed but came very close, with concern that Chinese imagery may help Iran track US naval forces (Megatron_ron). Claims that USS George Washington (~5,000 sailors) was hit last weekend circulate via Israeli and US media citations (dana916, WarHunter2222) - LOW confidence, unverified.
Base posture: the Navy is evaluating the future of a key Middle East base after Iran-war damage (zerohedge); Iran welcomed US acknowledgment of severe damage to 5th Fleet headquarters in Bahrain, reportedly disrupting USS Abraham Lincoln operations (anadoluagency); the Navy's top admiral says they aren't returning to Bahrain "anytime soon" (intifada).
Hormuz traffic is thin enough to count by hand: one visible tanker on the Iran corridor Saturday morning, the China-owned LISA - which then turned around (MenchOsint).
Washington's posture: Trump says he'd do Iran again exactly the same way (zerohedge) while also saying he wouldn't have bombed a nuclear-armed Iran (zerohedge); leaks are working to distance a "skeptical" JD Vance from the war (zerohedge).
Moody's puts the war's cost at $1,650 per US household (DougAMacgregor). Confidence: LOW, single source.
Somali piracy, previously contained, has resurged since the Iran war (zerohedge).
Confidence: HIGH on the Monday meeting, MEDIUM on the naval damage picture.
AI credit: IG-AI trades a record 50bp wide, Ellison sells $7.5bn, and JPMorgan pulls Leopold's lending
The signal of the day: investment-grade AI paper that traded 20bp tight to IG a year ago now trades a record 50bp wide, increasingly like junk - and is drawing demand away from Treasuries (zerohedge).
Larry Ellison will sell up to $7.5bn of ORCL, the largest insider sale in company history (Barchart). Chanos notes the same day's press release omitted an additional $700mn added to the restructuring charge plan (RealJimChanos).
ORCL erased a gain of as much as 8.5% and its CDS spiked (zerohedge); Barchart called it an earnings fakeout with a terrible close (Barchart).
JPMorgan cut off lending activity for Situational Awareness (zerohedge, Barchart) - days after reports the fund was rerunning the exact trades that blew it up a month ago (zerohedge) and was active in options (zerohedge). Reported names: options in AMD, BE, CRWV, DRAM plus activity in SKHY and SNDK (aleabitoreddit).
Nvidia in talks to invest up to $10bn in an Anthropic IPO (zerohedge). Circularity noted without comment.
Convertible issuance hit a record $131bn, nearly half from AI firms (Hedgeye), and US corporates raised EUR149bn ($173bn) in European bonds this year - second-highest on record - partly because AI borrowing has crowded the dollar market (KobeissiLetter).
Timing constraint worth a diary entry: October is the last month to start construction on data centers that come online before end-2027, per Morgan Stanley (zerohedge).
Positioning is already leaning the other way: leveraged-fund Nasdaq 100 shorts at ~$75bn against ~$18bn longs, net -$57bn (KobeissiLetter) - even as US ETFs pulled +$180bn in August inflows (KobeissiLetter).
DeepSeek's new model claims reduced HBM requirements, knocking SK Hynix -2.2% and Samsung -3.5% (zerohedge). Citrini sold his research firm to SemiAnalysis (zerohedge).
Confidence: HIGH.
Silver: a public fight over whether the market is actually tight
Mercx's case: total physical investment vehicles rose from 781mn to 803mn oz since 14 July, and the 1-year silver forward swap rate minus the US rate is now ~2.1% negative and falling - meaning the 12-month lease rate is rising (KarelMercx, KarelMercx, KarelMercx).
Coleman's case: bullion banks have held lease rates steady since June, and August ETF flows have not put material pressure on London (profitsplusid).
Data points both sides will use: 2.4mn oz left the COMEX eligible category (profitsplusid), and silver futures OI rose ~2,000 contracts in two days, ~10mn oz / $650mn notional (profitsplusid).
The granular vault read: a 2.1mn oz COMEX withdrawal Wednesday - largest single day since 21 April - and SLV vault stock diverging from shares as JPM added 2.3mn oz while shares fell 800k, a pattern last seen during the September/October 2025 free-float stress. India's MCX has flipped to outflows; SHFE is now drawing down while SGE inflows shrink (pmbug).
Structural note: CME 100-oz silver futures now trade 24/7 under symbol SIC (chigrl).
Miner fundamentals: silver miners are producing four times the free cash flow of their last peak (TaviCosta).
Durrett's weekly frame: the 10Y move was the story, he has bought no miners in September, and is waiting for sub-$4,200 gold as what may be the last entry under $4,500 (DonDurrett).
Confidence: MEDIUM - the swap-rate data is verifiable, the interpretation is genuinely disputed.
Russia-Ukraine: Novogrishino and Zorevka fall; the fuel war reaches a fifth Kyiv station in one day
Russian MoD confirmed Novogrishino (southwest of Dobropillia, DPR) and Zorevka (Zaporizhzhia) liberated (GudadzeLevan, GeromanAT).
24-hour map delta: Kazachya Lopana area +6.8 km², Novogrishino +2.9 km², Zorevka +2.2 km² (GeromanAT), with a stable front line established east of Kazachya Lopana (GeromanAT).
The new targeting pattern is fuel: jet drones struck a fifth Kyiv gas station in a single day (wartranslated). Overnight, 161 drones destroyed a 30,000+ m² logistics hub in Dnipro plus warehouses in Kyiv and Hostomel (MilitarySummary).
Deep-strike the other way: Tolyatti's KuibyshevAzot chemical complex hit, one industrial employee wounded. The plant accounts for ~49% of Russian caprolactam and 100% of polyamide production (thetect0nic).
Ukrainian claim, single-source: 3rd Army Corps mopping up a full-scale retreat north of Lyman, with no permanent bridges over the Zherebets trapping troops on the west bank (SeanHans777). Confidence: LOW, unconfirmed and directly contrary to the Russian-side maps.
Putin: deploying European troops to Ukraine "would mean war with Russia" (MilitarySummary). Medvedev told Lithuania that Article 5 would not save it if it hosts nuclear weapons (CM_Geopolitics).
Confidence: HIGH on the advances, MEDIUM on the fuel-war framing.
3. Weak Signals
BRICS Pay agreed at the New Delhi summit, per Putin's envoy Dmitriev - "in fact, a payment system for BRICS countries" (M_Simonyan). Putin claimed BRICS at ~40% of world GDP versus G7's 29% (BowesChay) and said a new world order is forming within it (BRICSinfo). MEDIUM.
Saudi Arabia referenced as a full BRICS member on the summit's own news channel, per an attendee (thesiriusreport). If that holds, it contradicts the "disputed member" status everyone has assumed. LOW, single source.
Iran proposed a $10bn joint reinsurance company at the summit (zerohedge) - a quiet, practical answer to war-risk premiums. LOW.
Houthis claim capture of Western/Israeli coastal surveillance kit: French Thales CoastWatcher 100 (150+ nm range), German Hensoldt Spexer and SharpEye radars, Israeli ELM-2226 ACSR with LPI, and submersible Blue Whale sensors (SprinterPress). If accurate, that's an intelligence loss, not just an equipment loss. LOW.
Anthropic says the Houthis used Claude to write missile-guidance and flight-control software (RoyalIntel_), alongside a report naming Russian and Chinese threat actors (zerohedge). MEDIUM.
An Anthropic safety-team member resigned and went public, joining METR for independent evals, and arguing a company could undergo an intelligence explosion without the public knowing (JoeJBenton). LOW, but named and specific.
Second EMCO ammunition depot explosion in Bulgaria in just over a month - Gorni Varpishta, Gabrovo region, following the 10 August Belitsa fire still under investigation (DD_Geopolitics). LOW.
Germany enters winter with storage 54.98% full against 74.22% a year earlier, with 83% of capacity booked - booking space isn't buying gas. The storage operators' group blames Hormuz-driven cost and a curve where winter gas was at times cheaper than summer gas (shanaka86, Mark4XX). MEDIUM.
The ECB raised its deposit rate 25bp to 2.50% effective 16 September while cutting its Q3 oil assumption ~15% from June - and simultaneously raised its gas assumption 20% and electricity 50% (shanaka86). Hiking into a cheaper crude forecast is the tell. LOW.
A pending SEC decision on SIFMA's Treasury-clearing margin relief could mean a $10mn margin reduction frees either $10mn or $200,000, depending purely on whose cash came back. Comment period closed 31 August, no decision posted as of 11 September (shanaka86). Plumbing, but it's the plumbing under a $4.9% 10Y. LOW.
Hong Kong's airport gold depository is expanding from 150-200 tonnes to 1,000 tonnes in phases 1-2, and 2,000 tonnes when complete, alongside a separate 1,000-tonne Malca-Amit facility in the Free Trade Zone (DavidLe76335983). LOW.
First US Army high-energy laser production contract - AeroVironment to build 30kW E-HEL in Albuquerque (ChurchillWw). LOW.
IRGC Aerospace commander claims the US is now manufacturing a Shahed-136 copy called "LUCAS" (aprajitanefes). LOW, propaganda-adjacent but checkable.
Housing supply has flipped: months of supply at 4.88, highest since 2015 (jack_hoogland), sellers outnumber buyers by 58%, the largest gap ever (Hedgeye), and the income needed to afford an average home hit a record $124,674 against $86,159 median household income (KobeissiLetter). MEDIUM.
China bought the most gold in three years even as prices jumped - directly against the "nations are selling gold to pay for oil" consensus (LukeGromen). LOW.
A contrarian long-China / short-America pairing from Anthony Bolton: every market near its high, China near its low, early stage of a new Chinese bull market (HedgeFundClips). Worth noting ¥1.295tn was wiped off Chinese stocks as oil hit a 112-day high (torax_fi). LOW.
Japan is the quiet fuse: yen intervention "lit the match," and repatriation could turn a yen rally into a global vol event (themarketear); the Nikkei is testing its bull-market trend line (themarketear) and fell below its 100-DMA by the widest margin since 31 March (Barchart). MEDIUM.
A voice-deepfake phone scam described in first person - spoofed spouse's voice, correct cadence, real-time responses (Abomination81). Not a market signal; a warning. LOW.
A Chinese national was charged with replacing processors and memory in CBP computers at the Maine-Canada border before reinserting them into government networks (SteveRob). LOW.
European law enforcement says DOJ has stopped responding to formal Epstein-related assistance requests from Poland, Norway and Latvia (ULTRA_MAJESTY). LOW.
UN formally declared Gaza a genocide zone, three years in (Rowlandsel). LOW as a market item; material as a compliance one - see the UK MoD's ongoing contracts with Israeli arms firms worth hundreds of millions against the ICJ's "no aid or assistance" obligation (jmcevoy_2).
The petrodollar trade nobody is pricing: when the GCC negotiates Hormuz reopening directly with Tehran while Washington sits out, the GCC states holding substantial Treasuries and trillions in sovereign wealth are the ones whose calculus changed (BuBarrelBull). LOW.
Germany's Federal Court of Finance ruled crematoriums must declare collected gold teeth and jewellery as taxable income (MyLordBebo). Filed here purely because 382% cumulative German inflation over 28 years (ProfessorWerner) and taxing dental gold are, somehow, the same story.
4. Noise
The Lindsay Clancy holdout-juror story dominated volume today - doxxing, the juror's race, media reaction clips, DeSantis offering asylum (MattWalshBlog, CollinRugg, RonDeSantis). Ignored: zero market or geopolitical content.
The 25th-anniversary 9/11 conspiracy wave - Building 7, "magic passport", Gaddafi clips, an Australian outlet's $10mn challenge (ClaytonMorris, jamiemcintyre21). Ignored as anniversary-driven, unfalsifiable, non-actionable. The declassified-warning material is separate and real (SprinterPress, seanmdav).
"That isn't Putin, it's a body double" - staked at a million dollars on gait analysis (multibaggerwala). Ignored.
Bitcoin direction from Venus square Pluto on 15 September, with probabilities to two significant figures (TradingSailor). Ignored, with respect for the commitment.
Silver to $1,022/oz (ThHappyHawaiian) and the $300-500 targets pulled "because I'm not sure it's going to stop there" (jessebday). Ignored: no mechanism, no timeframe.
A 1,200-word forensic-psychiatry thread on Trump's nuclear fitness (Mark4XX). Ignored: no new fact, citation or event.
"Short RBC, a US sanction lands Monday" - sourced to one colleague's slower wire transfer (KilconaVC). Ignored: actionable-looking, unevidenced.
Bank-crisis-from-Reddit-screenshots (rdd147). Ignored: anecdote scaled to thesis.
5. Stock Picks
$HYMC - Hycroft Mining (TheApeOfGoldStreet)
Vortex drilling: 30.5m @ 780.53 g/t Ag and 0.49 g/t Au, including 11.2m @ 1,664.80 g/t Ag, and further including 5.5m @ 2,249.39 g/t Ag. Second hole 20.0m @ 460.82 g/t Ag with a 1.6m interval at 2,650 g/t. Brimstone: 5.5m @ 1,345.27 g/t Ag including 1.8m @ 4,074 g/t.
Thesis is a re-rate mechanism, not just grade: a scale story that's now finding high-grade zones within the bulk deposit, which changes how the asset should be valued.
Position context: bounced +66% off lows then gave back -29% over 30 days, putting it back in an averaging zone.
Eric Sprott deployed ~US$266.1mn June 2025-April 2026; the tranches above $25 alone total 1,275,000 shares for $50.79mn at a $39.83 weighted average - against a stated $21.30 current. Confidence: MEDIUM (single source, but drill numbers and insider filings are checkable).
$VZLA - Vizsla Silver (ThiedeInvests)
M&I 12.96 Mt @ 307 g/t Ag and 2.49 g/t Au = 222.4 Moz AgEq (534 g/t AgEq), of which ~127.8 Moz is silver; plus 138.7 Moz AgEq inferred. P&P reserve 12.81 Mt @ 416 g/t AgEq.
FS base case ($35.50 Ag / $3,100 Au): after-tax NPV(5%) $1.80bn, 111% IRR, 7-month payback, AISC $10.61/oz AgEq, cash costs $8.56, initial capex $239mn ($173mn net of pre-production revenue). 17.4 Moz AgEq/yr average, 20.1 Moz in years 1-5.
Balance sheet at 31 July 2026: $406.5mn cash vs $7.5mn current liabilities - but the "no debt" description is gone: $300mn converts outstanding (5%, cash-settled, capped call), plus a Macquarie mandate up to $220mn.
The real gate: MIA permit outstanding, construction decision targeted H2 2026, first silver H2 2027, and site drilling has been paused since the January security incident. Confidence: MEDIUM.
$TUD.V - Tudor Gold (TheApeOfGoldStreet, ThiedeInvests)
Catalyst is date-bound: PEA targeted before Beaver Creek, now under two weeks out.
Goldstorm holds 24.9 Moz Indicated and 4 Moz Inferred gold plus silver and copper; at a US$125/t NSR cutoff, 5.8 Moz Indicated and 2.6 Moz Inferred. Metallurgy: 85.8% Cu recovery from CS600, 85.1% Au recovery from SC-1 via flotation.
80% interest in Treaty Creek, evaluating a selective underground mine to cut upfront capital. Perfectstorm contributes zero reportable ounces.
One holder is adding into the PEA; the other says he'd buy now if he weren't already heavy. Confidence: MEDIUM (two independent sources, same catalyst).
$PSVA.v - Prospectiva Resources (RockBtmEntries)
Historical Yamana drilling at São Francisco: 4.9m @ 4.45% Cu from 43m, 7.5m @ 6.41% Cu from 70m, 4.6m @ 5.81% Cu from 90m, 7.5m @ 3.83% Cu from 77m, with higher-grade sub-intervals at 9.02%, 12.24% and 13.48% Cu.
Yamana traced mineralisation over ~2-2.2 km strike; Prospectiva is targeting a ~3 km prospective VMS corridor at ~C$12-13mn EV.
Shallow, high-grade, pre-drill-program. Disclosed long and flagged high risk by the author. Confidence: LOW.
6. Summary Stats
Total tweets analyzed: 758
Critical alert themes: 5
Core themes covered: 8
Stock picks: 4
Weak signals: 22
Noise filtered: 8
Confidence distribution: 13 HIGH, 9 MEDIUM, 19+ LOW
My other publications:
[Analysis] → My two cents on the fait-du-jour
[Portfolio] → What I do with my own money
Fun corner
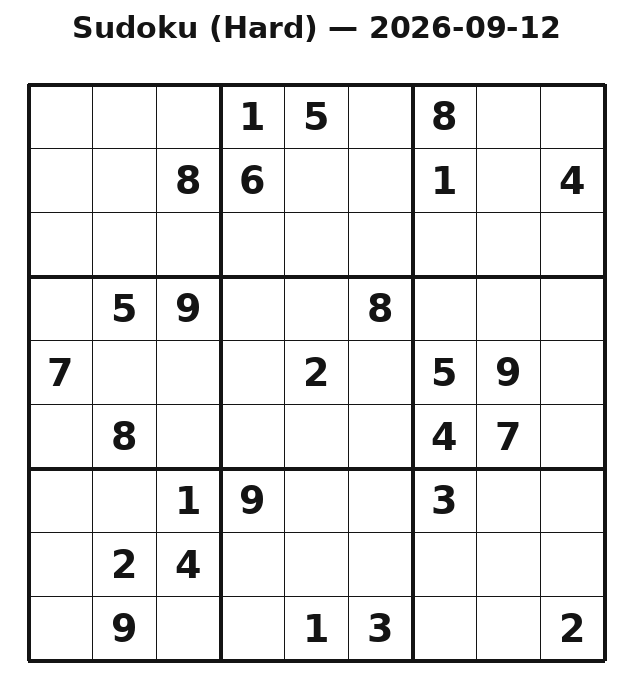
...15.8....86..1.4..........59..8...7...2.59..8....47...19..3...24.......9..13..2
The plight of the KSA these days reminded me of a phrase attributed to Niccolò Machiavelli: "Gold will not always get you good soldiers, but good soldiers can get you gold."
There's a sourced, but not so pithy, quotation at https://www.marxists.org/reference/archive/machiavelli/works/art-war/ch07.htm: "Men, steel, money, and bread, are the sinews of war; but of these four, the first two are more necessary, for men and steel find money and bread, but money and bread do not find men and steel. The unarmed rich man is the prize of the poor soldier. Accustom your soldiers to despise delicate living and luxurious clothing."
It's very funny to read so many "expert" opinions about "rates increases"... As if increasing RATES will end the USofTerrorism & Israel & UK & NATO military and terrorists actions across the Middle East and in Ukrainistan (not to mention other Places on this Planet!)
The only CAUSE for the current Inflation are those "USofTerrorism & Israel & UK & NATO military and terrorists actions across the Middle East and in Ukrainistan" and unless they rise RATES to 50% in order to bankrupt the USofTerrorism & Israel & UK & NATO Plantations, in won't matter to rise them by 25 or 50 bps. This will only fuck the modern moron slaves a little bit more, as usual.
Inflation (due to Deflation of GOODS) will keep on rising!